Westace Withdrawal: Processing, KYC and Payout Signals
 Available in GB
Contents
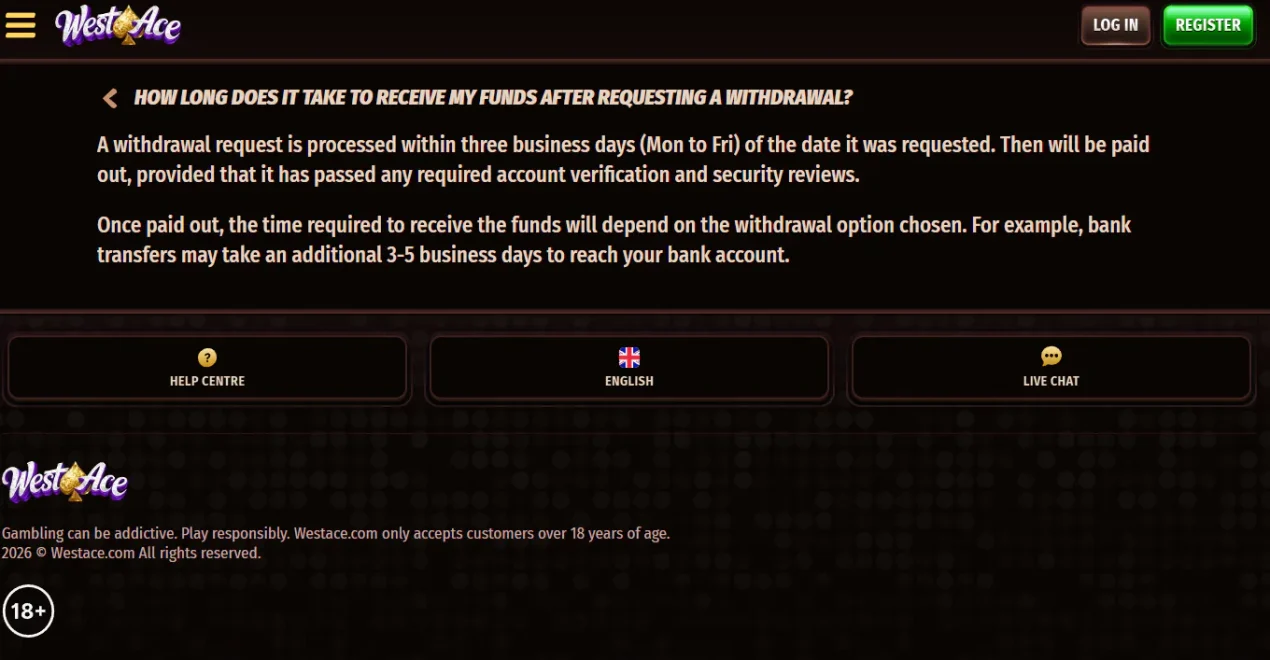
Westace’s current General Terms say its financial department works through withdrawal requests within three business days, provided the required checks and other conditions are complete. That is a general internal processing window, not a promise that money will arrive in a UK bank or wallet within three days. The public cashier page leaves exact UK and GBP withdrawal methods, method-specific settlement times, fees and GBP limits to the live account view. Recent customer reviews frequently discuss payout delays, but those reports describe individual experiences rather than proving misconduct. The safest UK-specific approach is to separate the official process from account-level cashier details and reputation signals.
Official process
How a Westace withdrawal moves from request to payment
The sequence matters when a payout takes longer than expected. A withdrawal can first depend on account and payment checks, then move to Westace’s finance review, and only after the operator releases it does the external payment method determine the final settlement stage. The published three-business-day wording applies to Westace’s finance processing, subject to the stated conditions; it is not a universal bank-arrival deadline. Keeping those stages separate makes it easier to identify whether an outstanding item is KYC, operator processing or payment-network settlement.
The useful starting point is Westace’s own General Terms. They describe a process in which the financial department works through a withdrawal request within three business days after the request is made, provided the other conditions are met and required checks are complete. The terms also make clear that further payment-system delays can happen after Westace has processed the request.
That wording creates four distinct stages. They should not be collapsed into one headline such as “three-day payout”, because each stage can add time or introduce a different dependency.
| Stage | What is supported by current Westace terms | What still needs to be checked for a UK account |
|---|---|---|
| 1. Withdrawal request | The customer submits a withdrawal using a method available on the account. | Which withdrawal methods are actually offered after the account country and currency are applied. |
| 2. Verification and account checks | Westace can delay a withdrawal while identity, account, source-of-funds or terms-compliance checks are completed. | Whether the account is already verified and whether an additional request appears at cashout. |
| 3. Finance review | The current terms give a general internal processing window of up to three business days once conditions and checks are satisfied. | This timing refers to the operator stage rather than a UK bank-arrival guarantee or method-specific settlement promise. |
| 4. External payment processing | The terms separate Westace’s finance review from delays that can occur after the payment instruction leaves that stage. | Ask the live cashier or support what the selected payment method normally shows for settlement and fees. |
This distinction is more useful than a single payout number. A withdrawal can be inside the operator’s stated internal review window while still taking longer to reach the destination, or it can be paused before finance processing because verification is incomplete.
When support gives a status update, ask which of these stages the request is actually in. “Pending”, “under review” and “processed” can sound similar in casual conversation, but they imply different next questions. If the account is still being checked, the useful issue is what information remains outstanding. If finance has completed its part, the useful issue is which payment rail now controls delivery. Keeping the stages separate makes follow-up more precise and avoids treating every delay as the same problem.
Verification dependency
KYC can sit directly in the withdrawal path
Westace’s current terms allow it to request identity, residence and payment-method or transaction evidence. They also say that verification is usually completed within 10 days after a complete response to the request, although the process can take longer depending on the circumstances and complexity. This is not a guaranteed cashout time and it should not be added mechanically to the three-business-day finance window.
The practical point is that verification and withdrawal processing are linked. If the requested documents or information have not been supplied, the operator’s stated finance timetable applies only after the required documents and information are in place. A first withdrawal can therefore involve a different sequence from a later withdrawal on an already checked account.
Prepare before cashout: use payment methods owned by the account holder, keep clear transaction records and make sure the personal details on the casino account are accurate. If Westace requests documents, respond through the official account or support route rather than sending them to an unrelated address.
The exact documents requested can depend on the account and the reason for the check. KYC requirements can pause a payout before finance review is complete.
UK and GBP unknowns
What remains unknown for a UK withdrawal
The current Westace payments page has Country and Currency selectors plus separate Deposit and Withdrawal controls, but the public payments page offers no confirmed United Kingdom plus GBP withdrawal set. That means exact UK withdrawal methods, GBP limits and local processing times remain unconfirmed until they appear for the relevant account.
Exact GBP minimums or maximums, UK fees, payout-method lists and bank-arrival times remain unknown until the live cashier supplies them. The General Terms contain withdrawal limits for a number of currencies, but GBP is not among the visible values in the relevant table. Converting a euro value into pounds would create a number that Westace itself has not published as a GBP rule.
Officially useful
- A general finance-processing window exists.
- Verification can delay processing.
- Payment-method availability can vary.
- Westace states that customer funds are held separately from operational funds.
Still account-level checks
- The exact GBP withdrawal limit.
- The exact UK withdrawal fee, if any.
- The precise withdrawal methods shown to the account.
- The settlement time after finance processing for the chosen method.
Before depositing, the live withdrawal tab should be compared with the intended deposit method. A visible payment brand in the banking overview is only a general signal; the live account must show the same route for a specific UK and GBP setup.
Recent withdrawal complaints
Recent withdrawal complaints need context, not automatic conclusions
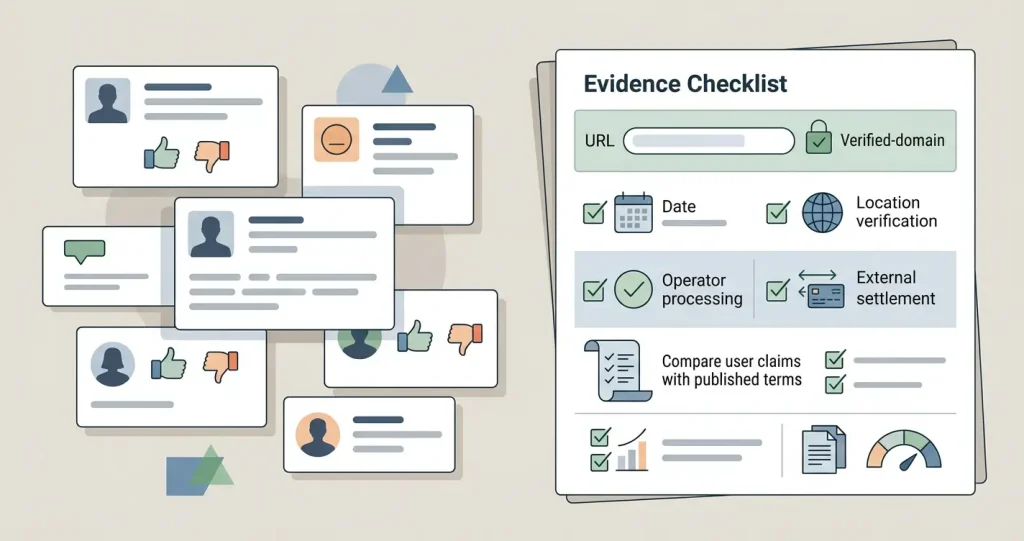
Recent westace.com customer-review listings include repeated complaints about withdrawal delays and support, including reports labelled as coming from Great Britain. The same review environment also contains mixed experiences rather than one uniform account of what happens to every customer.
Customer-submitted reviews are useful for identifying questions to ask. They are not suitable for proving that a casino has committed fraud, breached a law or will treat a future withdrawal in the same way. A review can be incomplete, inaccurate or based on circumstances that are not publicly visible, including verification, bonus conditions or payment-provider delays.
Recurring payout complaints make withdrawal handling worth closer examination before any deposit. It serves a different purpose from Westace’s own terms for the formal process, and it serves a different purpose from a regulator register for licensing questions.
Westace reviews add complaint patterns and positive experiences, while the published withdrawal terms remain the baseline for the formal payout process.
Funds wording
Separate-funds wording should not be confused with UKGC protection
Westace’s current General Terms state that customer funds are kept separate from operational funds in dedicated client bank accounts. That is an operator statement about how the brand says it handles customer balances.
It is important not to stretch that wording into a different claim. A corresponding licence record is required before Westace can be described as UKGC licensed, covered by a UKGC customer-funds category, or protected by a particular Great Britain insolvency arrangement. Those are separate regulatory questions.
Local licensing and consumer-protection scope belong to the licence and trust assessment. The withdrawal terms describe the operator process; local regulatory protection requires separate evidence from the licence and trust assessment.
Pre-withdrawal checklist
Six checks that reduce uncertainty before requesting cashout
- Finish any required account checks early. A withdrawal can be paused for identity, residence, payment-ownership or source-of-funds checks, so verification can arise again at withdrawal rather than only during registration.
- Read the live withdrawal tab. Confirm the exact method, currency, limit and fee shown to the account. Keep figures from the euro table in euros unless Westace publishes a GBP value.
- Keep the internal and external clocks separate. Westace’s three-business-day wording concerns its finance processing stage. The eventual payment method can have its own delivery time after that stage.
- Preserve the request details. Note the date, amount, method and status shown when the withdrawal is submitted. This creates a clear reference if support later needs to clarify what stage the request has reached.
- Keep bonus conditions separate from ordinary cashout rules. If a balance came from a promotion, check whether wagering or other promotion-specific conditions affect withdrawal before submitting the request.
- Escalate questions using official channels. Start from westace.com rather than a similarly named third-party domain, and keep copies of material correspondence about the transaction.
These checks help explain the stage of a delay, while payment speed still depends on verification, operator processing and the payment method. They do make it easier to tell the difference between an account check, an operator finance review and a payment-method delay, which is the key distinction between the published withdrawal stages.
When a deposit is still under consideration, run the same checklist in reverse: identify the withdrawal route first, confirm that its currency and account-ownership requirements fit the intended setup, and only then decide whether the deposit route is convenient. That approach gives cashout equal weight with funding instead of treating withdrawal as something to investigate only after a win.
Westace withdrawal FAQ
How long does a Westace withdrawal take?
Westace’s current terms say the financial department works through withdrawal requests within three business days once the relevant conditions and checks are met. That is not a guaranteed bank-arrival time because verification and external payment processing can add time.
Does Westace require KYC before withdrawal?
Westace can require identity, residence and payment or transaction evidence, and its terms allow withdrawals to be delayed while verification is completed.
What is the Westace withdrawal limit in GBP?
An exact GBP withdrawal limit is not shown in the current public information. Check the live withdrawal interface for the value attached to the account and method rather than converting a limit published in another currency.
What do bad reviews indicate about Westace payouts?
No. Recent payout complaints are a material reputation signal and a reason for caution, but customer reviews alone cannot support a legal or technical conclusion about every withdrawal.
UK withdrawal summary
What to Know Before Requesting a Westace Withdrawal in the UK
The three-business-day wording is best read as an operator-processing statement, not as a guaranteed end-to-end arrival time. A withdrawal can move through account checks, document requests and finance review before any external payment processing begins. Westace can request identity, residence and payment or transaction evidence, and its terms say verification is usually completed within 10 days after a complete response, although it can take longer. Exact UK or GBP withdrawal methods, limits, fees and method-specific settlement times remain separate live-account checks.
The formal withdrawal process is one part of the broader Westace review, alongside casino features, bonuses, mobile access and UK status.
The published withdrawal terms establish the general three-business-day finance-processing window, the ability to pause cashout for verification and the separation between operator review and later payment-system delivery. The exact UK and GBP method list, limits, fees and method-specific settlement times still belong in the live cashier check. Recent complaints make payout handling worth extra attention, but they remain customer reports rather than proof of wrongdoing. Before depositing, confirm that the expected withdrawal route is visible to the account and that the conditions that can trigger additional checks are clear.
This material was created by the Westace information team.
Related posts
Westace Official Site: westace.com and Domain Checks
Westace Reviews and Reputation: Withdrawals, Support and Customer Feedback